Article Brief
Discover the updated Standard Deduction for Salary, Pension, and Family Pension for 2025-26 to maximize your tax savings!
As the Finance (No. 2) Act, 2024 comes into effect from 1st April 2025, significant changes have been made to the standard deductions available to individuals earning income from salaries and family pensions. This article delves into the revised provisions for Assessment Year (AY) 2025-26, compares them with the current rules applicable for AY 2024-25, and explains how these deductions can impact taxpayers under different tax regimes.
1. Standard Deduction from Salary:
Under Section 16(ia) of the Income-tax Act, individuals earning salary income are entitled to a standard deduction. This deduction is allowed to reduce the taxable portion of their salary, offering relief to taxpayers without needing to provide any specific documentation.
For AY 2024-25:
- The standard deduction allowed is ₹50,000 or the amount of the salary, whichever is lower.
For AY 2025-26 (as per the Finance (No. 2) Act, 2024):
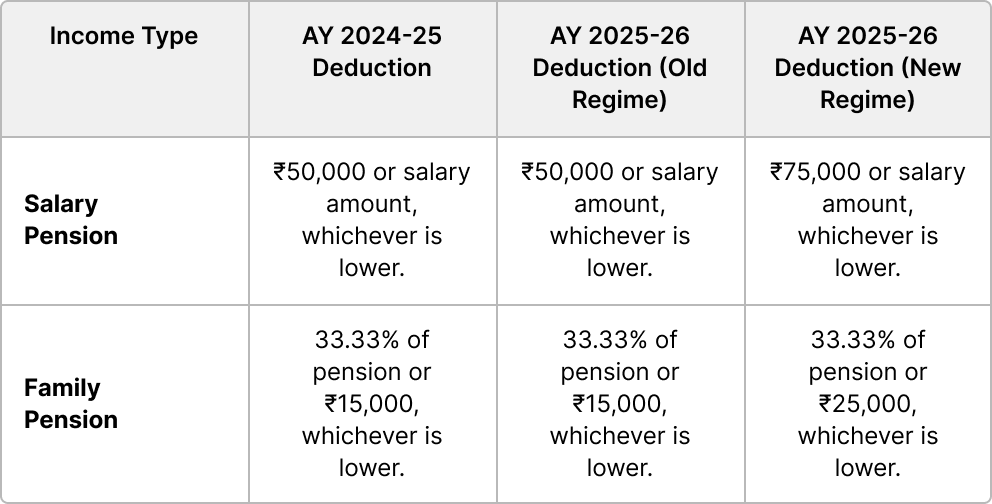
- In cases where income tax is computed under the Old Tax Regime, the standard deduction remains the same: ₹50,000 or the salary amount, whichever is lower.
- However, for those opting for the New Tax Regime under Section 115BAC(1A)(ii), the standard deduction has been increased to ₹75,000 or the salary amount, whichever is lower.
This enhancement in the deduction under the New Tax Regime is aimed at making it more attractive for salaried individuals who opt for the simplified tax structure without claiming exemptions and deductions.
Example:
- Mr. A earns a salary of ₹12,00,000 annually.
- For AY 2024-25: Mr. A is eligible for a standard deduction of ₹50,000. Thus, his taxable salary income will be ₹11,50,000.
- For AY 2025-26: If Mr. A opts for the Old Tax Regime, the deduction remains ₹50,000. However, if he chooses the New Tax Regime, the deduction increases to ₹75,000, reducing his taxable income to ₹11,25,000.
2. Standard Deduction from Pension:
Pension income is taxed under the head "Salaries" for tax purposes. Hence, retirees receiving a pension can also claim the standard deduction as per Section 16(ia).
For AY 2024-25:
- The standard deduction for pensioners is ₹50,000 or the amount of the pension, whichever is lower.
For AY 2025-26:
- Pensioners are entitled to the same benefits as salaried employees. If they opt for the New Tax Regime under Section 115BAC(1A)(ii), they can claim a deduction of ₹75,000 or the pension amount, whichever is lower.
Example:
- Mr. B receives an annual pension of ₹8,00,000.
- For AY 2024-25: He is eligible for a standard deduction of ₹50,000, reducing his taxable pension income to ₹7,50,000.
- For AY 2025-26: Under the New Tax Regime, he can claim a deduction of ₹75,000, reducing his taxable income to ₹7,25,000.
3. Standard Deduction from Family Pension:
Family pension, which is a regular monthly payment made to the family members of a deceased employee, is taxed under the head “Income from Other Sources” and not under “Salaries.” The standard deduction under Section 57(iia) applies specifically to family pension income.
For AY 2024-25:
- The deduction allowed from family pension is 33.33% of the pension amount or ₹15,000, whichever is lower.
For AY 2025-26 (as per the Finance (No. 2) Act, 2024):
- The deduction limit is enhanced to 33.33% of the family pension or ₹25,000, whichever is lower, if the taxpayer chooses the New Tax Regime under Section 115BAC(1A)(ii).
- This increase in the deduction for family pensioners is a significant relief for those opting for the New Tax Regime.
Example:
- Mrs. C receives a family pension of ₹8,00,000 annually.
- For AY 2024-25: She can claim a deduction of ₹15,000 (as it is lower than 33.33% of ₹8,00,000), reducing her taxable income to ₹7,85,000.
- For AY 2025-26: If she opts for the New Tax Regime, she can claim a deduction of ₹25,000, lowering her taxable income to ₹7,75,000.
Comparison Summary:
Conclusion:
The Finance (No. 2) Act, 2024 brings welcome changes for salaried individuals, pensioners, and family pensioners, particularly for those opting for the New Tax Regime. With the increased standard deductions under Section 16(ia) and Section 57(iia), taxpayers can enjoy greater relief in reducing their taxable income. These changes will be effective from AY 2025-26 and should be considered when planning for tax-saving strategies.
Taxpayers should carefully evaluate whether to opt for the Old Tax Regime with its various deductions and exemptions or the New Tax Regime with higher standard deductions and lower tax rates but fewer tax-saving options.
Prosperr.io is a simple platform to manage your personal income tax. It helps you save and automates tax tasks. It gives you the knowledge to make smart financial choices, keeping your money where it belongs.
Click here to book your FREE tax assessment call
Disclaimer:
The information provided in this article is for general informational purposes only and does not constitute legal, tax, or professional advice. Readers are advised to consult with a qualified tax advisor or legal professional for specific advice tailored to their individual circumstances, particularly regarding reassessment proceedings and claiming refunds. The author and publisher are not responsible for any errors or omissions, or for any actions taken based on the content of this article.